10 Nov
Half-year results 2027: Strong order growth and revenue momentum underpin full-year expectations
Oxford Instruments plc today (10 November 2026) announces its interim results for the six months to 30 September 2026.
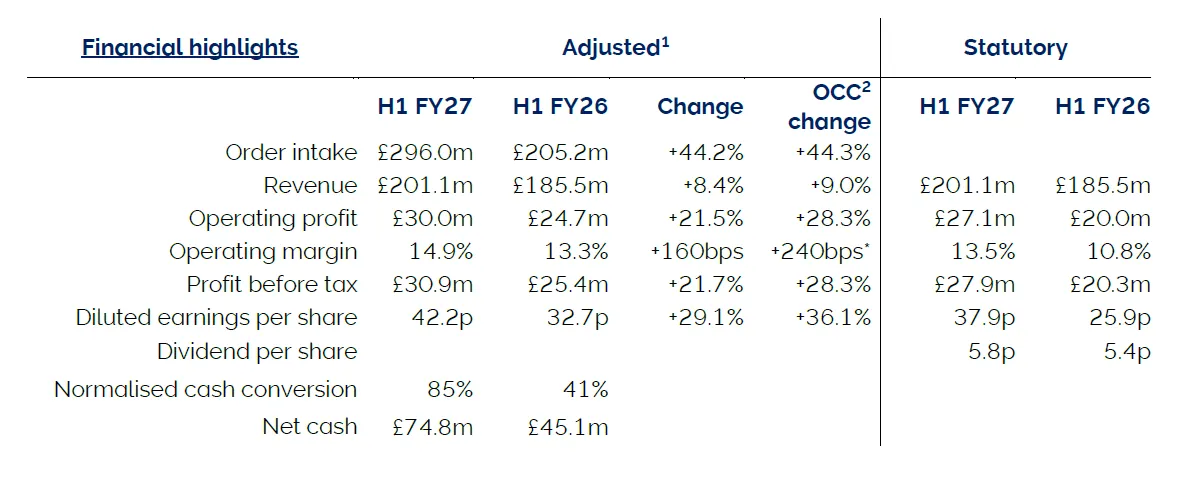
Financial highlights
- Group order intake up 44% and order book of £317m underpin H2 delivery:
- I&A: Order intake growth 12% and order book up 8%, providing good cover going into H2
- AT: High volume manufacturing (HVM) customers driving 126% order intake growth, with full order cover for FY27 and building well into FY28
-
- Commercial order intake up 20%, driven by semiconductor and materials analysis applications. Regional sales model supported the stronger order growth; investments made in new customer demonstration centres in Korea, Taiwan and Germany
- Academia intake grew 2.8% OCC despite ongoing softness in US life science academic research
- Multiple high-volume manufacturing customer wins, as they choose our differentiated compound semiconductor process technology as they ramp for global demand for datacentre infrastructure
- Investment in operational capacity including strategic supply chain initiatives, cleanroom optimisation, ongoing productivity improvements and planned skilled labour increases
- Revenue is now expected to grow c. 20%
- Margin is expected to move up into our medium target range of 12%-15%
- 1. Definitions of the Group’s Alternative Performance Measures can be found in note 3 to the Interim Financial Statements
- 2. Organic constant currency (OCC), as defined in Note 3 to the Interim Financial Statements.
- 3. Book-to-bill is defined as orders received in the period divided by revenue in the period.
- 4. The mean of consensus estimates for reported full-year FY27 results are for revenue of £446.1m, adjusted operating profit of £81.2m, and adjusted operating margin of 18.2%. Please refer to the Company website for more details of how consensus is calculated.
Group revenue growth of 9.0% OCC with AT growth of 26.6% OCC following strong execution; I&A up 3.1% OCC with order book replenished post strong deliveries in Q4 FY26
- AOP up 21.5%, despite £1.7m FX headwind. AOP margin up 160bps (+240bps OCC) to 14.9%, with both divisions improving margins versus a softer H1 FY26
- Diluted adjusted EPS growth of 29% due to the higher profit and accretive impact of the ongoing share buyback programme
- Step up in free cash flow to £19.1m (FY26: £0.2m), driven by strong operating cash conversion of 85% (H1 FY26: 41%) and by reduced restructuring and zero pension contributions
- £74.8m net cash at the end of the period; £83.1m of £100m share buyback programme complete by 30 September 2026. Remaining £16.9m expected to be completed in early 2027; intention to then extend by £25m to Summer 2027
Strategic and operational highlights
• Global market strength in compound semiconductors, and continued structural growth in material sciences drove high demand from commercial customers in these segments
• Good progress continues in I&A:
• AT scaling to meet exceptional demand:
• Continued R&D investment in line with target at c. 9% of revenue driving innovation, new products and software upgrades, including a focus on integrating AI capabilities
• Strong balance sheet provides optionality in line with our capital allocation priorities, which include ongoing organic investment, dividends, M&A and further share buybacksCurrent trading and outlook
• The Group continues to trade in line with market expectations for FY27
• For FY28, the strength of the Advanced Technologies order book and expected new order intake improves our outlook for this division:Richard Tyson, Chief Executive Officer of Oxford Instruments plc, said:
“We have had a very encouraging first half, with strong order momentum. Through the continued delivery of our strategy, our talented teams are building a platform for sustainable growth, significantly extending our commercial customer base, while continuing to enable Nobel Prize-winning academic research.
Read the full results statement
“We are seeing good momentum in Imaging and Analysis, despite the challenging macro landscape and pressure on US academic spend. We continue to invest in the front end of the business to maximise our opportunities for organic growth into H2 and beyond.
“In Advanced Technologies, high-volume manufacturing customers across the world are choosing our compound semiconductor processes to support the delivery of datacentre and communications infrastructure. We are focusing on ensuring we have the capacity, supply chain and service model needed to execute on this demand.
“While remaining mindful of the ongoing complexity of the external landscape and the challenges of rapid growth, given the growth in our order book, we are confident in our ability to meet market expectations for the full year, and are on track for our medium-term goals.”We expect to provide a further trading update on 14 January 2027.
Notes: